Central Bank Operations
Monetary Management
- MAS’ monetary policy framework is centred on managing the Singapore Dollar against a trade-weighted basket of currencies. This is also known as the S$NEER.
- As part of MAS’ monetary operations, MAS manages:
- the S$NEER through intervention operations (IO) in the spot foreign exchange (FX) market; and
- Singapore Dollar liquidity in the banking system through money market operations (MMO) and liquidity facilities.
- MAS may accumulate or expend Official Foreign Reserves (OFR) through its IO, by purchasing or selling US dollars against Singapore dollars.
- MAS uses a range of MMO instruments to inject or withdraw liquidity, including: (i) MAS Bills; (ii) direct borrowing or lending; (iii) repurchase agreements (repos) on Singapore Government Securities (SGS); and (iv) FX swaps.
- MAS incurs interest expense in its conduct of MMO as liquidity is typically withdrawn from the banking system. The interest expense incurred is a function of the amount of MMO carried out and the prevailing Singapore Dollar interest rates.
- The amount of MMO depends on a range of factors, including the amount of IO conducted, the net amount of public sector cashflows (including issuance and redemption of SGS and related securities), the growth of banks’ deposit liabilities, and banks’ demand for reserve balances with MAS.
- The level of Singapore Dollar interest rates is influenced by a range of factors, such as global interest rates and market expectations of the strength of the Singapore Dollar.
- In FY2023/24, MAS incurred net cost of S$9.2 billion in its conduct of MMO, after offsetting interest income from Reserves Management Government Securities (RMGS).
Reserves Management Government Securities
- As part of monetary policy implementation, MAS may accumulate OFR in excess of the amount it requires for the conduct of monetary policy and support of financial stability, i.e. the optimal size of OFR of about 65% to 75% of GDP.
- Under such circumstances, MAS may subscribe to RMGS to transfer OFR above what it requires, to the Government for longer-term management by GIC. This enables such foreign assets to be invested in longer-term, higher-yielding assets.
- In FY2023/24, MAS’ transferred S$22.5 billion to the Government for management by GIC, with outstanding RMGS holdings increasing from S$237.6 billion to S$260.1 billion. MAS received S$9.7 billion in interest income from its holdings of RMGS. RMGS interest income is a function of the amount of RMGS and prevailing Singapore Dollar interest rates.
Currency Translation Effects
- As MAS’ financial results are reported in Singapore Dollars, currency movements of the Singapore Dollar against foreign currencies of the OFR will result in translation effects in MAS’ financial statements. Currency translation effects are thus a consequence of MAS’ conduct of exchange rate-based monetary policy. These currency translation effects have no impact on the international purchasing power of the OFR, or on MAS’ ability to conduct monetary policy and support financial stability.
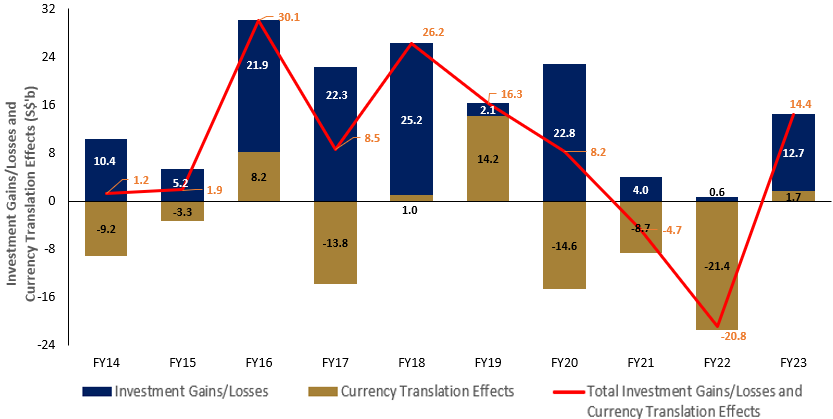
- In FY2023/24, currency translation effects were positive and amounted to S$1.7 billion, due primarily to a weakening of the Singapore Dollar against the US Dollar, Euro and Pound Sterling.
- The currency translation effects (brown bars) over the past 10 years are shown in Chart 1.
Size and Composition of OFR
- MAS held S$497.6 billion (US$368.7 billion) of OFR as at 31 March 2024.
- MAS periodically assesses the optimal size of OFR necessary to conduct monetary policy and support financial stability in Singapore. The optimal size of OFR is currently estimated at 65% to 75% of GDP. OFR in excess of the amount that is needed by MAS will be transferred to the Government for longer-term management by GIC through the subscription of RMGS by MAS.
- The OFR is invested in a well-diversified portfolio of cash, bonds, equities, and commodities that provides sufficient liquidity to conduct monetary policy and support financial stability. The portfolio is also diversified across advanced and emerging market economies, and across different currencies.
- Investment-grade bonds in the advanced economies form the largest allocation in the portfolio. About three-quarters of the OFR is denominated in the US Dollar, Euro, Japanese Yen, and Pound Sterling, with the bulk in US Dollar.
- The strategic allocation of the portfolio is reviewed periodically to ensure that the liquidity, risk, and investment objectives continue to be met as market conditions change. The portfolio aims to be resilient to risks across market conditions, while also providing good stable long-term sustainable returns.
Investment Performance
- In FY2023/24, MAS recorded an investment gain of S$12.7 billion. Global markets generally rebounded, particularly in the second half of the financial year amidst resilient global growth and moderating inflation. The investment gain was mainly from interest income, dividends and realised gains from the management of OFR, offset by valuation provisions. Compared to the previous financial year, all major asset classes including developed markets and emerging markets bonds and equities posted higher returns.
- The total investment gains/losses and currency translation effects, as represented by the dark red lines in Chart 1, was an overall gain of S$14.4 billion in FY2023/24.
- The investment gains/losses (blue bars) over the past 10 years are shown in Chart 1.
Chart 1: Investment Gains/Losses and Currency Translation Effects
Risk Management
- The MAS Board approves the investment universe and risk management framework.
- Investments are subject to risk limits and controls, and MAS conducts stress tests regularly to manage financial risks.
- MAS monitors investment risks closely and reports them regularly to the MAS Board and Risk Committee.